 United States
The investment community has been tying itself in knots over climate change.
For several years, political pressure, for example in multiple US states, has encouraged many investors to step away from analysing the topic, at least publicly. At the same time, the relative underperformance of many climate-oriented portfolios has encouraged views that there is an intrinsic trade-off against financial returns.
Yet there has been a rapid uptick in the number and severity of wildfires, floods and droughts that damage or destroy return-generating assets.1
Arguing that climate change isn’t a major overarching cause of these events, with the potential to become much more severe, is increasingly indefensible. Irrespective of investors’ views on climate change or climate policy, however, the financial materiality of climate risks (and opportunities) cannot be ignored. To manage them effectively, investors need to be crystal clear that they need to be treated no differently from any others.
Reflecting on a climate of confusion
A quarter of a century ago, the potential impact of climate change was only narrowly understood. A handful of investors (large and small) looked to reduce the emissions associated with their investments, seeking to “help protect the planet”. In parallel, others recognised that a changing climate would, directly or indirectly, lead to new business opportunities and risks.
Both objectives were and remain legitimate, but they are not the same. Muddling the two has created problems for both investment decision-making and communication.
For instance, greenhouse gas emissions are a poor proxy for investment risk, and ‘impact investors’ aiming to reduce them across their portfolios have generally missed their financial targets. Our own analysis finds that low-emission stocks underperformed between January 2017 and March 2026.2
Excluding high-emitting stocks also inadvertently creates significant sector and factor tilts, which are often a cause of lagging investment returns. This was particularly severe as equity markets narrowed dramatically between 2023 and 2025, when the combined share of the 10 largest S&P 500 stocks increased from 26% to 41% of the US index.3
Poor relative performance, combined with growing political scrutiny, made climate-oriented approaches increasingly difficult to defend. But abandoning climate analysis because some investment approaches have disappointed draws the wrong conclusion.
Focusing now on financial materiality
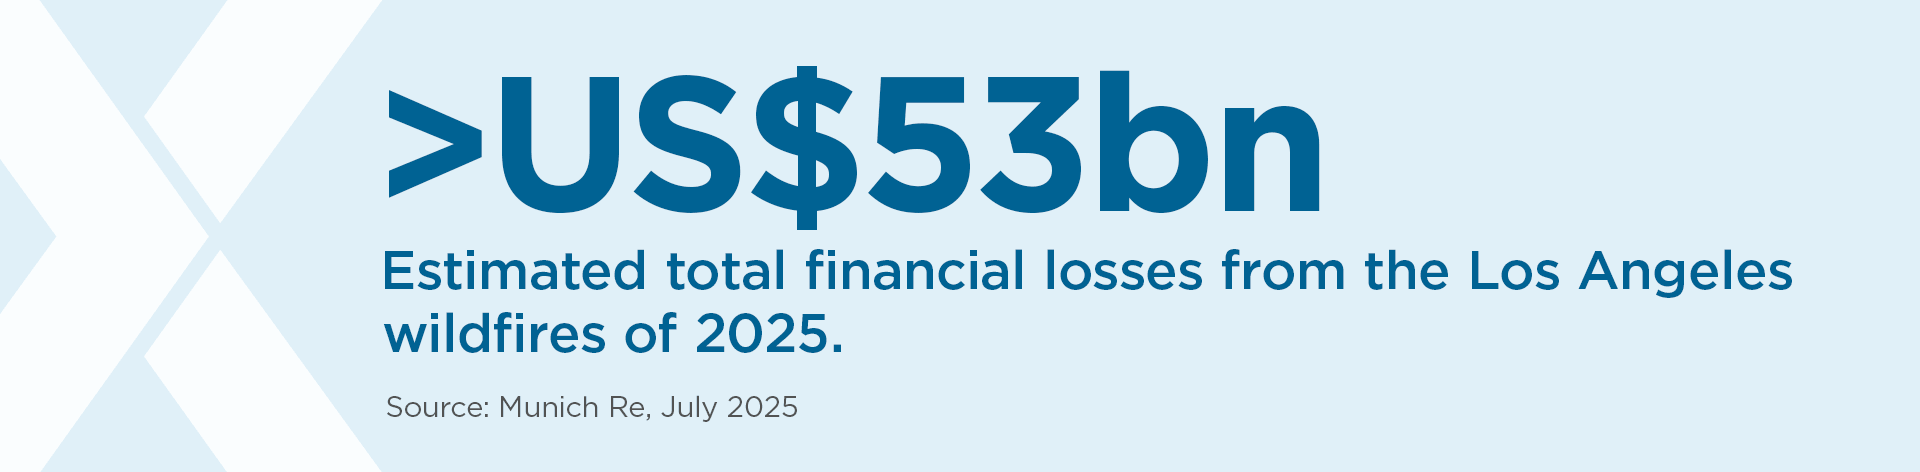
As summer 2026 in the Northern Hemisphere draws to an end, investors are no doubt reflecting on the consequences of widespread and tragic floods, fires and droughts. The financial costs have yet to become clear, but recent events highlight the scale of potential losses: the drought affecting the Rhine in 2018 reduced German GDP growth by 0.4 percentage points, while total losses from the Los Angeles wildfires of 2025 were estimated to be at least US$53bn.4,5
The investment question is not simply whether a company is exposed to climate change, but how that exposure reaches its financial statements and ultimately the value of its securities. I believe those managing money should focus on three priorities.
1. Translate climate change into financially material issues
For near- and medium-term analysis, investors should move beyond “climate change” as the headline analytical framework. Instead, they should focus on topics affected by it that are uncontroversially material to the economy, particularly: extreme weather; markets for clean energy, transportation and energy efficiency; and resource availability and pricing, including water.
Analysis should investigate the implications for corporate strategy – including organic growth, capital expenditure and M&A – and corporate risk, including physical risk, policy risk and competitive advantage. The critical question is how these issues alter revenues, costs, margins, asset values, capital requirements and competitiveness.
Whatever their views on climate policy, investors need to assess financially material issues such as extreme-weather exposure, water shortages, electricity demand and insurance availability.
2. Treat government climate policy as an investment variable
Rather than asking whether a policy is “good for the climate”, investors should analyse its financial consequences. For instance, how does a new emissions trading scheme affect a company’s cost base? Do stricter building codes increase demand for particular products? How do changes in insurance markets shape asset values?
These are all questions – like similar others pertaining to energy, transport and water policy – that can be incorporated into the analysis leading to earnings forecasts and valuations.
3. Retain climate change as a multi-decade risk framework
Over shorter periods, the focus can be on identifiable transmission mechanisms affecting companies, markets and security valuations. Over decades, however, climate change is a major, potentially dominant uncertainty with the scope to profoundly affect, most likely damage, all areas of society either directly or indirectly.
Pension plans, whose beneficiaries will likely be alive in such conditions, surely have an obligation to consider how the evolution of environmental conditions, technology, markets and policy may evolve as a result.
Framing climate appropriately
The same distinction should guide how investors communicate with their stakeholders.
With beneficiaries, they should be clear whether they are seeking to optimise risk-adjusted returns, reduce associated emissions, or both – and, if so, how they address conflicts between the two. Equally, they should also be prepared to explain how they’re assessing longer-term scenarios and managing the risk that benefits are impaired.
With investee companies, engagement should challenge corporate strategy and the management of financially-material risks.
With policymakers, investors should focus on policies affecting connected topics such as clean energy, building codes and effective insurance markets.
With the media, they should explain the underlying material investment issues – growth markets, weather risk, resource availability or policy – rather than relying on “climate change” as shorthand.
Changing the language does not mean disguising climate change because it has become politically contentious. It means being more precise about the ways in which it affects investments.
As investors, let’s sidestep the politicisation of climate change, alter the language where necessary, and rapidly step up the focus on how to assess and manage its consequences.
1 National Centers for Environmental Information / Climate Central, 2026: Billion-Dollar Weather and Climate Disasters
2 Impax analysis, June 2026. Based on MSCI ACWI index data for the period of 30 December 2016 to 31 March 2026
3 S&P Global data, 2026
4 Mooney, A. et al., 17 August 2026: The economics of Europe’s drought. Financial Times
5 Munich Re, July 2025: Wildfires around Los Angeles, severe thunderstorms: US natural catastrophes dominate global losses in the first half of 2025. Other estimates of total losses from the LA wildfires are as high as US$164bn
References to specific securities are for illustrative purposes only and should not be considered as a recommendation to buy or sell. Nothing presented herein is intended to constitute investment advice and no investment decision should be made solely based on this information. Nothing presented should be construed as a recommendation to purchase or sell a particular type of security or follow any investment technique or strategy. Information presented herein reflects Impax Asset Management’s views at a particular time. Such views are subject to change at any point and Impax Asset Management shall not be obligated to provide any notice. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary. While Impax Asset Management has used reasonable efforts to obtain information from reliable sources, we make no representations or warranties as to the accuracy, reliability or completeness of third-party information presented herein. No guarantee of investment performance is being provided and no inference to the contrary should be made.