 United States
As Europe and North America recover from summer heatwaves and drought, east Asia braces for yet more tropical storms. An especially strong El Niño weather pattern in the Pacific is proving conducive to a busy typhoon season, with five severe storms making landfall within a two-week period in late August 2026.1
While ‘sustainability’ issues may have fallen down the agenda within parts of the Asian investment community, as elsewhere, we perceive growing focus on corporate and issuer resilience – how robust companies’ strategies and business plans are in the context of evolving challenges. This includes to extreme weather risks exacerbated by climate change.
An extensive roadshow meeting investors across Asia earlier this month has only reinforced this impression. It also underlined two other connected ways in which the sustainability story is evolving in the region, too. We outline all three below.
1. The focus on ‘resilience’
Most Asian investors recognise that climate change presents material risks and opportunities: 70%, according to a survey by the Asia Investor Group on Climate Change.2 A growing number have adopted nature-related strategies, too.3
The framing relating to these issues has evolved to ‘resilience’ for many investors. This aligns well with our own decision last year to use the terms ‘corporate’ and ‘issuer resilience analysis’ to describe our proprietary analysis of material risks across equities and fixed income.
Many of the threats to corporate and issuer resilience are, of course, sustainability-related – such as those arising from physical climate risks and biodiversity loss, or resource scarcity – but extend to adjacent risks like supply chain vulnerabilities and technological disruption. Energy security is understandably in focus across much of the region – as it is in Europe – given geopolitical volatility and disruption to the global energy trade.
‘Resilience’ itself has become a multi-layered term in our industry, but in this context of understanding risks and opportunities, we believe the shift is entirely appropriate as it implicitly demands a focus on financial materiality. The question of which businesses are best positioned for the economic, technological and resource constraints of the future is one that has preoccupied our listed equities team for decades.
2. The Asia-led AI infrastructure build-out
Few conversations between investment managers and clients conclude these days without mention of AI. Given the extent to which the theme has dominated the trajectory of global equities over the past three years, this is understandable.
Investors are increasingly looking past the early ‘winners’ of the AI trade – primarily US software and cloud computing leaders – to the companies whose technologies provide the foundations for the AI build-out.
The data centres that power AI applications consume enormous amounts of electricity and water.5 Continuous operations and narrow operating parameters demand ultra-reliable grids and cooling systems.
Many of the companies that dominate markets for the advanced power management and heat control systems on which data centres worldwide rely are Asian. In parallel, the region is also at the heart of semiconductor manufacturing, electronic supply chains and industrial automation.
For investors focused on the region, the ‘AI story’ is therefore not simply about owning technology companies, but also identifying the companies solving the power, water, cooling, infrastructure and resource constraints to enable the global AI build-out. In this sense, it highlights too how traditional boundaries between ‘technology’ and ‘sustainability’ have blurred.
3. The demand for decision-useful sustainability analysis
There is a growing recognition among asset owners that physical climate risks remain systematically underpriced.6 As elsewhere, we perceive that investors in Asia increasingly want to understand how sustainability risks translate into corporate earnings, capital expenditure and operating costs.
Backward-looking measures such as a company’s current carbon footprint can be useful context, but on their own tell us relatively little about whether a business is prepared for future technological, regulatory or physical disruption.
It is more financially material to understand whether a company is building a more resilient business model. How exposed is it to energy or water constraints? Does it have credible capital expenditure underpinning its climate transition plan? How vulnerable are its factories and supply chains to extreme weather?
Several Asia-specific dynamics sharpen investors’ minds in the region. According to analysis by Swiss Re, emerging Asian economies are among those most vulnerable to physical climate risks.7 Densely populated coastal cities, in particular, face rising exposure to rising sea levels, flooding and severe storms.8 The financial losses are real and present: a recent investor study, for example, found that climate-related hazards already cost Asia’s major electricity utilities an estimated US$6.3bn each year.9
Across the region, we observe that companies are enhancing their decision-useful sustainability reporting in response to investor expectations, regulation and disclosure standards like the Task Force on Climate-related Financial Disclosures (TCFD). A 2026 study reveals adoption is far from universal, though: while 98% of Taiwan-listed companies report in line with TCFD guidelines, for example, the figure is only 30% among companies listed in mainland China.10
For asset managers, the challenge is not to produce more sustainability data, but to generate better financially material insights from sustainability analysis. Where data is still patchy, we believe there is an important role for company engagement.
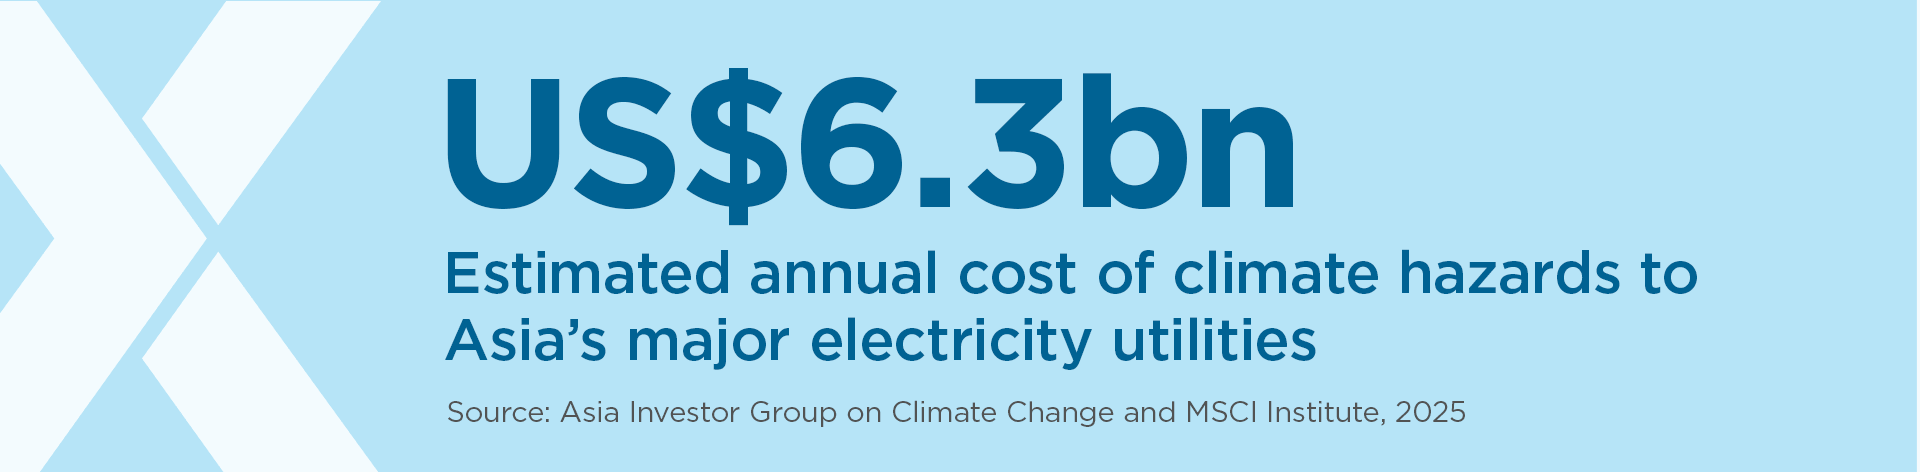
All eyes on the future economy
Decades working in Asia leave no room for the misconception that the region’s investment market is remotely homogenous. The structure of Australia’s superannuation system bears little resemblance to Japan’s retail distribution model, and so forth.
If there is one thing that these diverse markets have in common, it is perhaps a shared focus on the future. Asian investors have a front-row seat: the region drove 69% of global GDP growth between 2015 and 2025.11
As the economy transforms and is propelled by AI, it must navigate rising resource constraints and physical climate risks; equities investors are understandably focused on identifying companies that boast resilience and competitive advantages.
We believe that sustainability-related factors will become increasingly material drivers of opportunities, as well as risks. With many Asian companies at the vanguard of providing solutions to environmental challenges, it is an exciting time to be focused on the region.
1 Maersk, 4 September 2026: East Asia typhoon season impacting logistics
2 Institute for Energy Economics and Financial Analysis, 2024: Sustainability in Asset Management in Asia: An Institutional Investor Perspective
3 Gambetta, G., 26 June 2025: How financial institutions in Asia are ramping up on nature. Responsible Investor
4 The 10 largest companies by market capitalisation accounted for 24.3% of the MSCI ACWI index as at 31 August 2026, up from 10.5% as at 31 January 2020
5 IEA, 2025: Energy and AI
Mytton, D., 2021: Data centre water consumption. Nature
6 MSCI, 2024: What the Market Thinks: A Climate Risk Survey / EDHEC Climate Institute, 2024: Physical climate risk survey
7 Swiss Re, 2021: The Economics of Climate Change: Impacts for Asia
8 AIA, August 2026: Climate and Health in Asia
9 Asia Investor Group on Climate Change and MSCI Institute, 2025: Asia’s Powerhouses at Risk
10 ISS Corporate, March 2026: Sustainability Reporting in Asia: Framework Adoption and Trends in Focus
11 World Economics, 2026
References to specific securities are for illustrative purposes only and should not be considered as a recommendation to buy or sell. Nothing presented herein is intended to constitute investment advice and no investment decision should be made solely based on this information. Nothing presented should be construed as a recommendation to purchase or sell a particular type of security or follow any investment technique or strategy. Information presented herein reflects Impax Asset Management’s views at a particular time. Such views are subject to change at any point and Impax Asset Management shall not be obligated to provide any notice. Any forward-looking statements or forecasts are based on assumptions and actual results are expected to vary. While Impax Asset Management has used reasonable efforts to obtain information from reliable sources, we make no representations or warranties as to the accuracy, reliability or completeness of third-party information presented herein. No guarantee of investment performance is being provided and no inference to the contrary should be made.